The Referees Refuse to Rig the Match: Inside Collision Week, the AI Debt Vacuum, and India’s $60 Billion Reserve Shield

A long-form deep dive into Episode 10 of the Currency Colosseum, decoding how global monetary authorities are navigating physical energy shocks, sovereign bond yield spreads, and tokenized financial plumbing.

The Pre-Collision Threshold: Five Central Banks in Seven Days
Imagine standing on the precipice of a global macroeconomic collision. In a span of just seven days, five major central banks are set to deliver interest rate decisions in a synchronized financial free-for-all. Across trading floors from London to Tokyo, precision-engineered monetary models are being tossed out the window as central bankers face an unprecedented convergence of physical energy inflation, sovereign yield stress, and technological debt issuance.
As 19th-century monetary historian Alexander Del Mar observed in his classic survey A History of Money in Ancient Countries:
“When the public treasury relies upon foreign exchange reserves to offset commercial trade deficits, every dollar sold from the vault is a temporary shield; the ultimate pillar of monetary stability remains the real productive output of the realm.”
Del Mar’s warning on foreign exchange reserves rings remarkably true today from Mumbai to Paris. Selling spot dollars from central bank vaults buys crucial time against global energy shocks, but when sovereign risk spreads widen, central banks must brace for structural friction as major monetary policy meetings collide.
The U.S. Dollar: The Pre-Collision Shift and the AI Debt Vacuum
To understand the international clashes unfolding during Collision Week, one must begin with the heavyweight anchor of the global monetary system: the U.S. dollar.
In recent weeks, global money markets executed a dramatic recalibration regarding the Federal Open Market Committee’s (FOMC) upcoming October 28 meeting. Money markets transitioned away from pricing in an immediate rate hike, shifting instead to an “extended hold” baseline in the 3.75% to 4.00% target range. However, market pricing reflects heavy expectations for interest rate tightening to resume at the December FOMC meeting.
Despite this near-term policy pause, the U.S. Dollar Index (DXY) remains exceptionally strong at 101.81. The dollar’s structural dominance is being sustained by two immense physical cost drivers:
- Persistent Energy Inflation: Brent crude oil remains stubbornly anchored above $105 per barrel, establishing an elevated inflation floor.
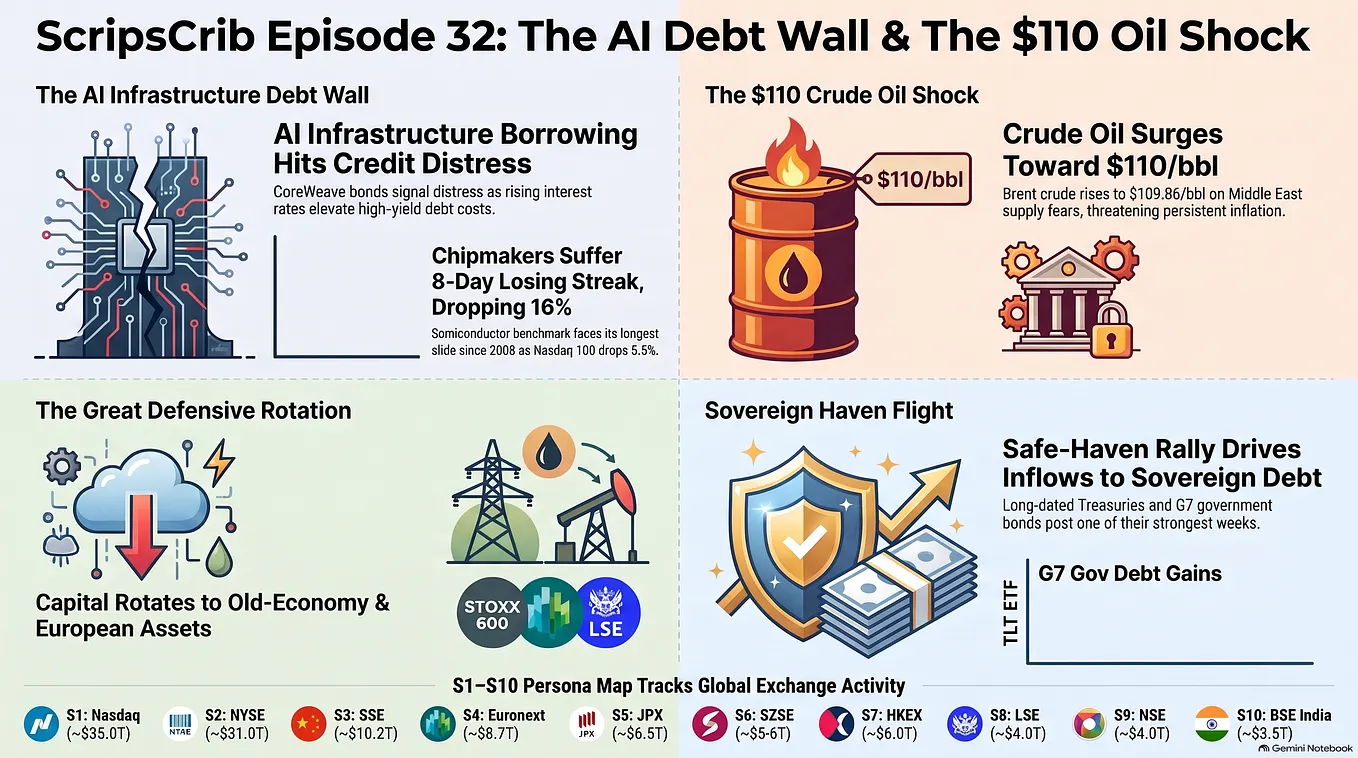
- The AI Debt Wave: The global boom in artificial intelligence technology infrastructure is vacuuming up immense volumes of credit market capital.

The Transcontinental Railroad Analogy
To visualize how technological expansion is reinforcing currency strength, consider the construction of the transcontinental railroad in the 19th century. As railroad tycoons borrowed astronomical sums to lay down physical steel tracks across the continent, that massive capital demand absorbed available credit across the economy.
Today, technology conglomerates are issuing staggering volumes of high-yield, dollar-denominated corporate bonds to finance concrete, advanced cooling systems, power grid connections, and gigawatts of electricity for AI data centers. Because global investors in Tokyo, London, and Frankfurt seek these high-yield, high-security dollar returns, they must first purchase U.S. dollars on the spot market. This creates a gravitational vacuum effect, pulling capital straight across the Atlantic and maintaining dollar scarcity worldwide.
The Euro: 2011-Era Yield Spreads vs. Tokenized Financial Plumbing
While the U.S. dollar operates as a high-yield capital vacuum, the eurozone is struggling to preserve domestic capital while confronting acute sovereign debt anxiety.
The Euro (€) has been testing critical support near 1.1202 amid slowing European private sector activity. However, the core vulnerability is a sharp flare-up in sovereign risk centered on France:
- French 24-Year Yield Peaks: French 10-year government bond (OAT) yields reached 5.0%, marking a 24-year high.
- Widening Risk Spreads: The risk spread between French OATs and German Bunds expanded to levels last observed during the peak of the 2011 Eurozone sovereign debt crisis, driven by parliamentary budget gridlock in Paris and geopolitical uncertainties in Eastern Europe.
The Tokenization Defense
To prevent European capital from fleeing toward high-yielding U.S. corporate debt, European Central Bank Executive Board Member Piero Cipollone has been championing the Capital Markets Union (CMU) and the tokenization of digital euro infrastructure.

Europe’s financial system remains fragmented across 27 national frameworks, making cross-border capital movement clunky and expensive. By placing European financial assets on a unified digital ledger, the ECB aims to make intra-European capital flows entirely frictionless. The strategy is clear: if European savings can move seamlessly within the continent, money is more likely to remain in Europe rather than seeking refuge in U.S. debt markets.
Get D Murali’s stories in your inbox
Join Medium for free to get updates from this writer.
However, a fundamental contradiction remains: can a high-tech digital token system resolve the analog economic realities of heavy government debt and political gridlock? With the ECB expected to hold interest rates at 2.65% to protect fragile economic growth, Frankfurt cannot raise rates to match U.S. yields without worsening sovereign fiscal stress.
The Indian Rupee: A $60 Billion Vault Defense and Macroeconomic Surgery
In contrast to verbal guidance in London or digital plumbing in Frankfurt, emerging markets are employing direct, heavy-handed intervention to defend against global energy shocks.
Facing a 46.3% jump in its national crude oil import bill ($90.6 billion) due to $105+ Brent crude oil, the Reserve Bank of India (RBI) executed a historic currency defense:
- Five-Week Reserve Drawdown: Over five consecutive weeks, the RBI deliberately drained $59.7 billion from its foreign exchange reserves, bringing total holdings down from a record peak of $785.7 billion to $726.0 billion.
- The Direct OMC Oil Dollar Window: To prevent state-owned Oil Marketing Companies (OMCs) from crashing the rupee by purchasing billions of U.S. dollars on the open spot market, the RBI created a private, off-market dollar window. Energy firms purchase dollars directly from the central bank’s national vault, keeping massive energy transactions hidden from public exchange order books.
- Foreign Exchange Risk Reserve (FERR) Rules: The RBI enforced a 20% reserve requirement on certain unhedged derivatives, forcing speculative traders to post significantly more capital to short the rupee.

These targeted measures successfully stabilized the USD/INR exchange rate within the ₹94.92 to ₹95.06 range, earning public backing from major industry body ASSOCHAM and buying crucial economic stability despite Middle East drone strikes on energy infrastructure.
Asian and Commodity-Linked Currencies: Defensive Pre-Positioning
Across the rest of the Asian continent and commodity markets, central banks are taking disciplined defensive stances ahead of Collision Week:
- Japanese Yen (¥): USD/JPY consolidated near 157.80. With national CPI reaching a 9-month high of 2.4%, the Bank of Japan is expected to maintain its rate at 1.25% while money markets price in an increasing likelihood of a December rate hike.
- Chinese Yuan (元): The People’s Bank of China (PBOC) maintained a tight vice-grip on its daily midpoint fixing near 6.7800, enforcing currency stability as Beijing hosted the 5th Plenum of the Communist Party.
- Canadian Dollar (🇨🇦) & Kiwi (🇳🇿): Commodity-linked currencies braced for policy reviews, with money markets pricing an 81% probability of a 25 basis point rate hike by the Bank of Canada (to 2.50%) and prospective tightening by the Reserve Bank of New Zealand (to 3.00%) to defend against capital outflows.

Conclusion: The Bizarre Intersection of Eras
The global monetary landscape is currently defined by a remarkable paradox. Central banks are combining ancient, historical brute-force tools — such as draining $60 billion from physical foreign exchange vaults — with futuristic digital tokenization architectures to combat distinctly modern crises, including AI data center debt crowding out credit markets.
Ultimately, this paradigm shift suggests that the next era of global economics may no longer be governed by central bankers casually turning traditional interest rate dials, but rather by who controls the physical energy resources and digital infrastructure of the future.

Bibliography
- Associated Chambers of Commerce and Industry of India (ASSOCHAM). (2026). Evaluation of RBI Foreign Exchange Stabilization Measures. New Delhi, India.
- Del Mar, Alexander. (1895). A History of Money in Ancient Countries from the Earliest Times to the Present. London: G. Bell & Sons.
- European Central Bank. (2026). Keynote Address by Piero Cipollone on Capital Markets Union Tokenization. Frankfurt am Main, Germany.
- Federal Reserve System. (2026). Statements by Governors Jefferson, Bowman, and Waller on the Economic Outlook. Washington, D.C.
- International Monetary Fund. (2026). Eurozone Sovereign Risk Spread Analysis and Fiscal Health Report. IMF Press Release, Washington, D.C.
- Reserve Bank of India. (2026). Statistical Supplement: FX Reserves and Foreign Exchange Risk Reserve Guidelines. RBI, Mumbai.