Why Digital Banks Are Becoming More Than Banks
What happens when a bank stops being a place to store money and becomes part of how people live, work, and run businesses?


Open your banking app on any given morning. You see your balance, sure. You also see where your money went this month: a pending international transfer, a business payment that just landed, and a savings option you didn’t know existed.
No branch. No queue. You probably don’t even think of it as “the bank” anymore. You just use it.
That small shift says a lot about where banking’s going.
For decades, a bank’s job was simple: hold deposits, process payments, and hand out loans. Digital banks are quietly rewriting that job description. To me, the bigger story isn’t that banking went digital. It’s that people now expect a bank to do more than it ever used to.
Banking isn’t about holding money anymore
Traditional banking was built around products. You opened an account, got a debit card, moved money around, and went to a branch when something broke.
The first wave of banking mostly copied that onto a phone screen. Useful,. It was only step one.
Today people want more. They want notifications, faster payments, access across borders, simple account management, and financial tools that fit into their daily routine instead of interrupting it.
Picture a business owner. Tracking payments, paying suppliers, and managing expenses across four different platforms is exhausting. Think of someone working with clients in other countries, who just wants to hold a few currencies and send money without a pile of hurdles.
The bank is slowly turning from a destination into a tool that runs in the background.
The real opportunity is connection
Here’s something I keep coming to.
A customer doesn’t care whether their payment travels through a banking network, an API, or some fancy payment infrastructure. They care about one thing: did the money arrive?
Businesses feel the same way. Nobody wants five providers for accounts, cards, payments, and financial management if one setup could handle it all.
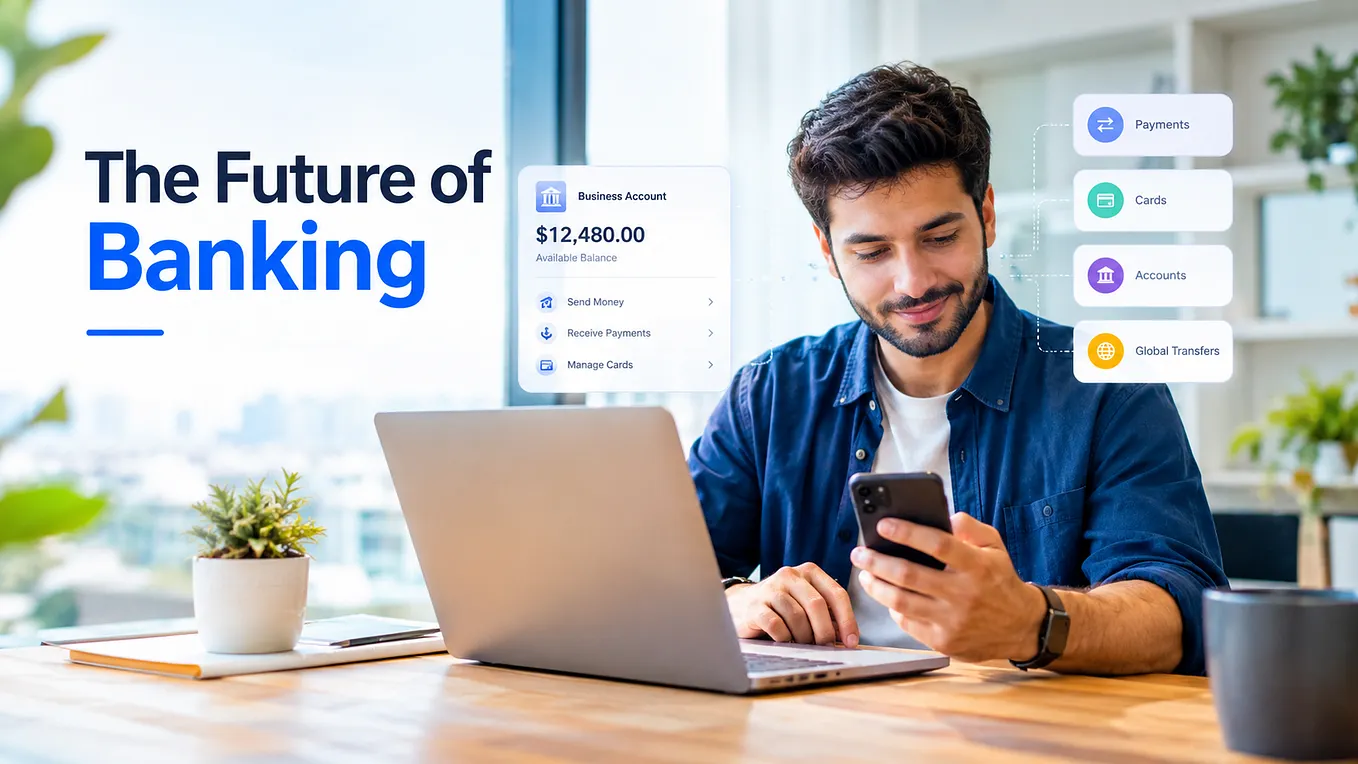
That’s why digital banking platforms have become so interesting. They can pull together:
- Digital accounts that are opened and managed online
- Card services for personal and business use
- Payment infrastructure for domestic and international transfers
- Multi-currency tools that help businesses operate across markets
Get Rachit Reflects’s stories in your inbox
Join Medium for free to get updates from this writer.
- Integrations with accounting software and other business apps
The value isn’t in having every feature. It’s in making them work together.
Infrastructure matters more than the app
Here’s what customers rarely see when they open a banking app: everything underneath it.
A polished interface can make a platform look impressive. The real work happens out of sight. Account connectivity, payment processing, security controls, compliance, transaction monitoring, and third-party integrations all shape the experience.
A digital bank can have an app and still struggle if the foundation can’t handle growth.
Imagine a fintech company expanding from one country into five. Suddenly it has to deal with currencies, payment networks, regulations, banking partners, and customer verification rules. Building the app was the part. Building something that works reliably across all those markets is a different problem.
Digital banks are becoming business partners
Something else is changing in business banking.
Small businesses, startups, freelancers and international companies need services that match how they actually operate. Many of them don’t want a “banking experience” at all. They want to receive money, pay suppliers, manage cards, and work across borders without friction.
That opens a door for banking platforms to become part of the business ecosystem. A company could build selected features straight into its own software so customers never have to visit a separate banking platform.
This is where embedded finance and Banking-as-a-Service come in. Financial services can now live inside platforms that were never designed to be banks.
Growth comes with responsibility
There’s a side of banking that doesn’t get enough attention: trust.
When people hand over their money, security and compliance can’t be treated as extras. Data protection, identity verification, transaction monitoring, fraud prevention, and regulation become part of the business itself.
Expanding into markets makes this even harder. A platform needs more than technology that works. It needs the partnerships, operations, and compliance framework to back it up.
Without that foundation, fast growth stops being an achievement. Starts being a risk.
So what will a bank look like?
I don’t think the future of banking is branches replaced by mobile apps. That change already happened.
The bigger shift is that banking is blending into life. People may access services through shopping platforms, business tools, payment products, or entire digital ecosystems without ever thinking about “going to the bank.”
The companies that get this will look past building another banking app. They’ll focus on infrastructure, connectivity, security, partnerships, and the customer experience.
Because the next generation of banking won’t be defined by where people keep their money. It’ll be defined by how they use it.
And maybe that’s the change of all: banking is moving from a service people visit to a system they use without noticing.